One question splits the whole delay
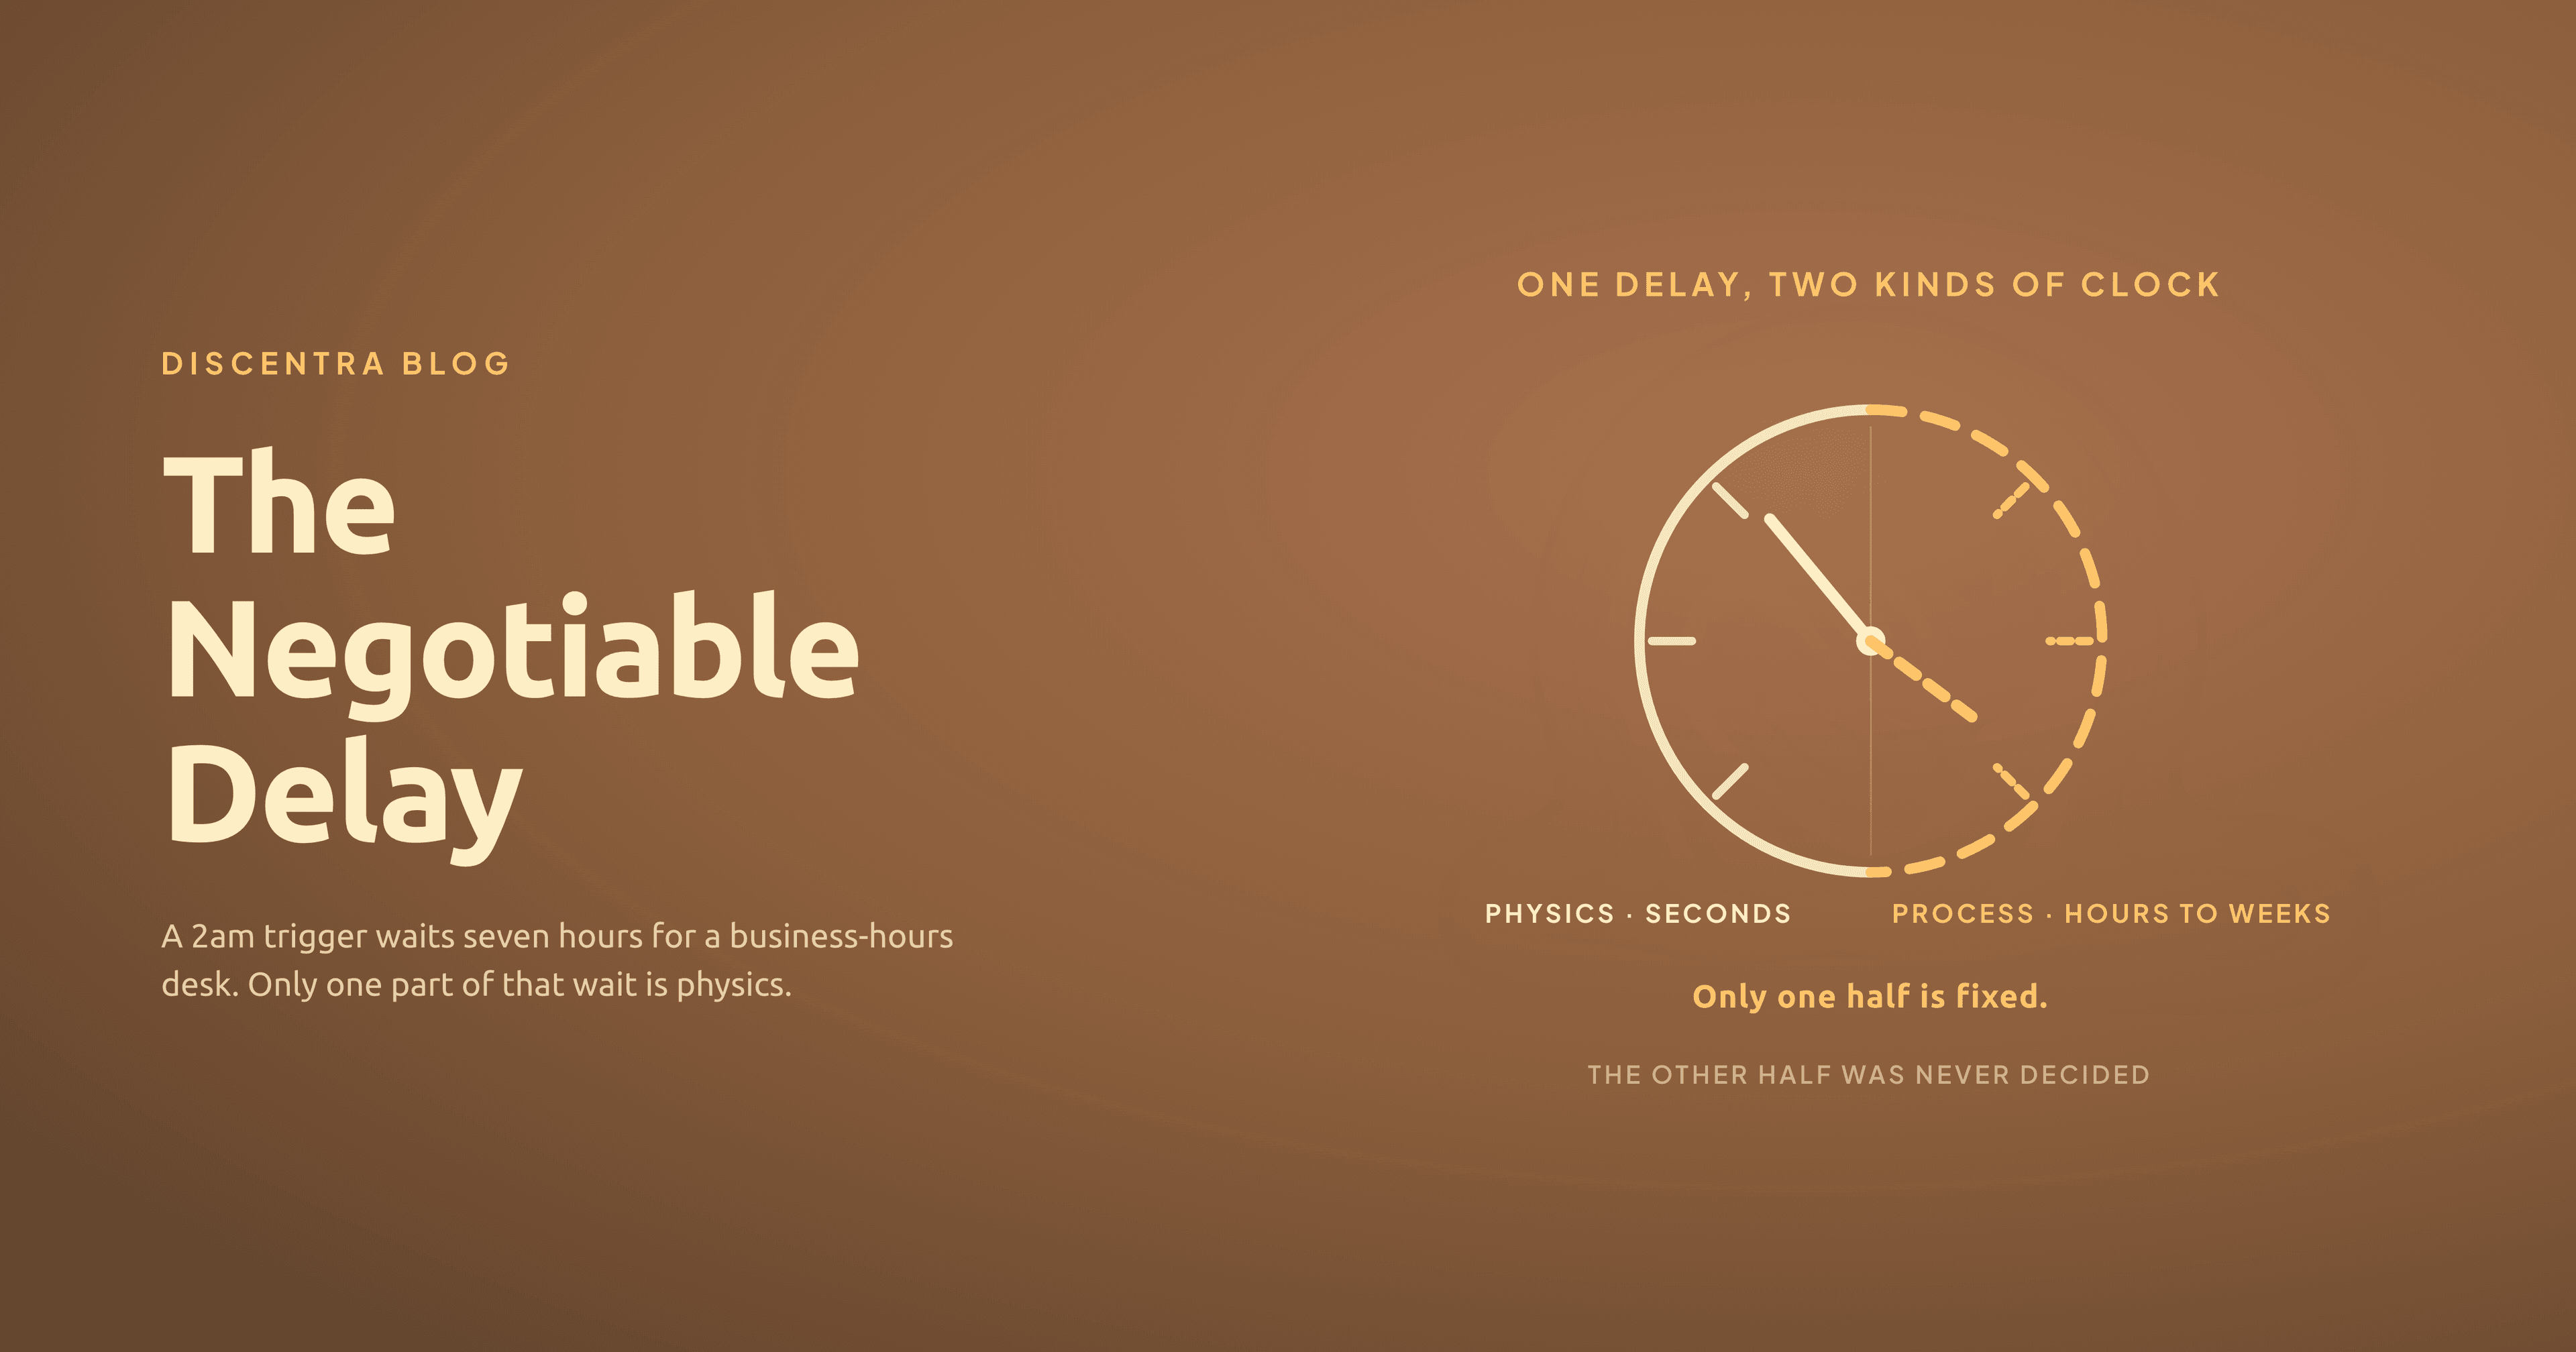
Ask one question of any delay: is it imposed by physics, or by process? A metallurgical cure time is physics. A form that waits for Thursday's sign-off meeting is process. The distinction matters because only the second kind is negotiable, and an organisation that never separates the two can end up treating the whole delay as a law of nature.
Run a trading firm's retention delay through that question and it separates cleanly.
When a trader takes a loss that matters, the response is fast. The body's fast stress arm releases catecholamines in seconds, and their half-life in the blood is one to two minutes. Our working definition of a revenge trade is a re-entry within a minute of the loss, at larger size, and a firm can check how often that pattern appears in its own fills. We operationalise the space between trigger and next trade as a window of roughly four minutes. The physiology is measured science. The four-minute figure is our working construct, not a measured figure.
The stress response is the whole physics half. Everything else in the delay belongs to the other column.
The clocks the firm chose
Walk through what a standard operation runs between a trigger and a response, and note when each one fires.
The one control that moves at event speed is the max-loss lockout, and it deserves its credit: it fires the instant losses cross the line. But it is positioned at the end of the sequence, enforcement at the crash boundary rather than intervention before it. It is real time at the wrong moment.
After the lockout, the clocks get long. The retention or support desk works business hours in one timezone. The trader's journal gets reviewed that evening, if it gets reviewed. The analytics dashboard is read the next morning, or on Monday. The cohort report lands monthly. The lapse flag, the one that says a funded trader has gone quiet, fires weeks after the behaviour that caused it. Every tool in that list works, and we have written before about the window they all miss. This post is about what stands between a firm and that window: each tool works on its own clock, and none of those clocks is set by the event it is meant to catch. At the macro scale the same gap shows up as the silence between the challenge sale and the blow-up. They are inherited cadences: office hours, reporting cycles, the rhythm of the working week, applied to a pattern that can run its course before the kettle boils. One clock on the trader's side has since been shortened by the industry itself: where a client can place an order from an AI assistant, the path from a loss to a live re-entry is a sentence and a yes, and the confirmation step on that path checks the order, not the trader.
The latency ledger
Put the clocks in one table and label each one.
| Clock | Typically fires | Physics or process? |
|---|---|---|
| Stress response | Seconds after the trigger | Physics |
| Next trade after a loss | Within a minute, on our revenge-trade rule | Our working definition |
| The intervention window | ~4 minutes | Our operational construct, built on the two rows above |
| Max-loss lockout | Instant, at the loss boundary | Process, positioned last |
| Retention / support desk | Business hours | Process |
| Journal review | That evening, up to ~19 hours | Process |
| Dashboard review | Next morning or Monday | Process |
| Cohort report | Up to 30 days | Process |
| Lapse flag | Weeks after the behaviour | Process |
The arithmetic makes the table concrete. A trigger fires at 2:14am: three losses, a re-entry at double size, the shape a risk desk would recognise. A desk that opens at 9:00 in the firm's home timezone can first act six hours and forty-six minutes later. Call it seven hours. The behaviour it needed to reach completed before 2:20am.
The assumption is stated so you can attack it: one desk, one timezone, 9 to 6. A firm running follow-the-sun coverage shrinks the number. It does not change the column the desk sits in, because the smallest process clock in the stack is still measured in hours, against an event measured in minutes.
How far spirals of this shape sit behind the churn that removes ~75% of retail traders inside 90 days is something a firm can check in its own trade data. The delay is not a detail of the problem. On the intervention side, it is the part a firm controls.
The industry already thinks this way, once
Trading has one of the most sophisticated latency cultures in any industry. Firms publish guides for shaving execution latency to a millisecond. Infrastructure vendors advertise tick-to-trade in microseconds. Evaluation rules police holding times measured in seconds. On the execution path, the sector treats every millisecond as negotiable and hunts it without mercy.
Then the intervention path runs on office hours and monthly reports, as if that were just how retention works.
The engineering instinct is not missing. It is pointed at the execution side, and the standard retention stack shows no sign of it. A seven-hour wait for a tilting trader is what those clocks add up to until someone splits the total into the half that is fixed and the half that is chosen.
An afternoon's audit
The exercise costs an afternoon. List every clock in your retention stack: every control, review, report and flag that could touch a struggling trader. Write down when each one actually fires relative to a trigger, not when the vendor deck says it does. Label each row physics or process.
Run on the standard stack above, the exercise gives one trader-side clock the firm cannot move, one fast control positioned after the damage, and every other firm clock in the process column, each with a cadence someone set and someone can change. Some of those rows can be re-sequenced with what a firm already owns: alerts routed to whoever is awake, reviews moved closer to the session. The last gap, the minutes between trigger and next trade, is the one no review cadence reaches, and it is the specific gap Discentra exists to close: detection on the trade feed, and a coaching call that arrives inside the window. Coaching, not financial advice.
But the audit stands on its own. Most of the clocks in the ledger are process, and an afternoon of labelling them is how a firm finds out which ones it can change.