The 30/70 split
We pulled a major prop firm's public Trustpilot reviews, 3,000+ in total with a 4+ average rating, and categorised each sampled negative review by primary complaint. 30% of negative reviews describe behavioural patterns: traders breaching drawdown limits under pressure, buying new accounts after failing the last one, quitting over rule changes they could not emotionally process. 70% describe operational issues: platform bugs, payout delays, KYC problems, support failures.
That is the headline finding. The 70% is infrastructure the firm can already see in tickets and logs. The 30% is psychology: unmeasured at almost every firm, and fixable without changing the platform, the pricing, or the rules.
The full breakdown, the methodology, and the limitations are all on this page, because a finding you cannot interrogate is not worth citing.
Why the churn rate hides this
Every prop firm knows its churn rate. The percentage sits on a dashboard somewhere, gets reported quarterly, triggers a marketing meeting. "Our churn is 12%." "We're down to 9%."
The rate tells you how many traders leave. It does not tell you why. And the why is where the money is.
A churn rate treats every departure as the same event. The trader who left because a payout took six weeks and the trader who left after failing three challenges in a tilt spiral land in the same spreadsheet row. Operational churn is legible to the org chart: a payout delay creates a ticket, a platform outage pages an engineer, a KYC backlog shows up in onboarding metrics. Somebody owns each of those failures.
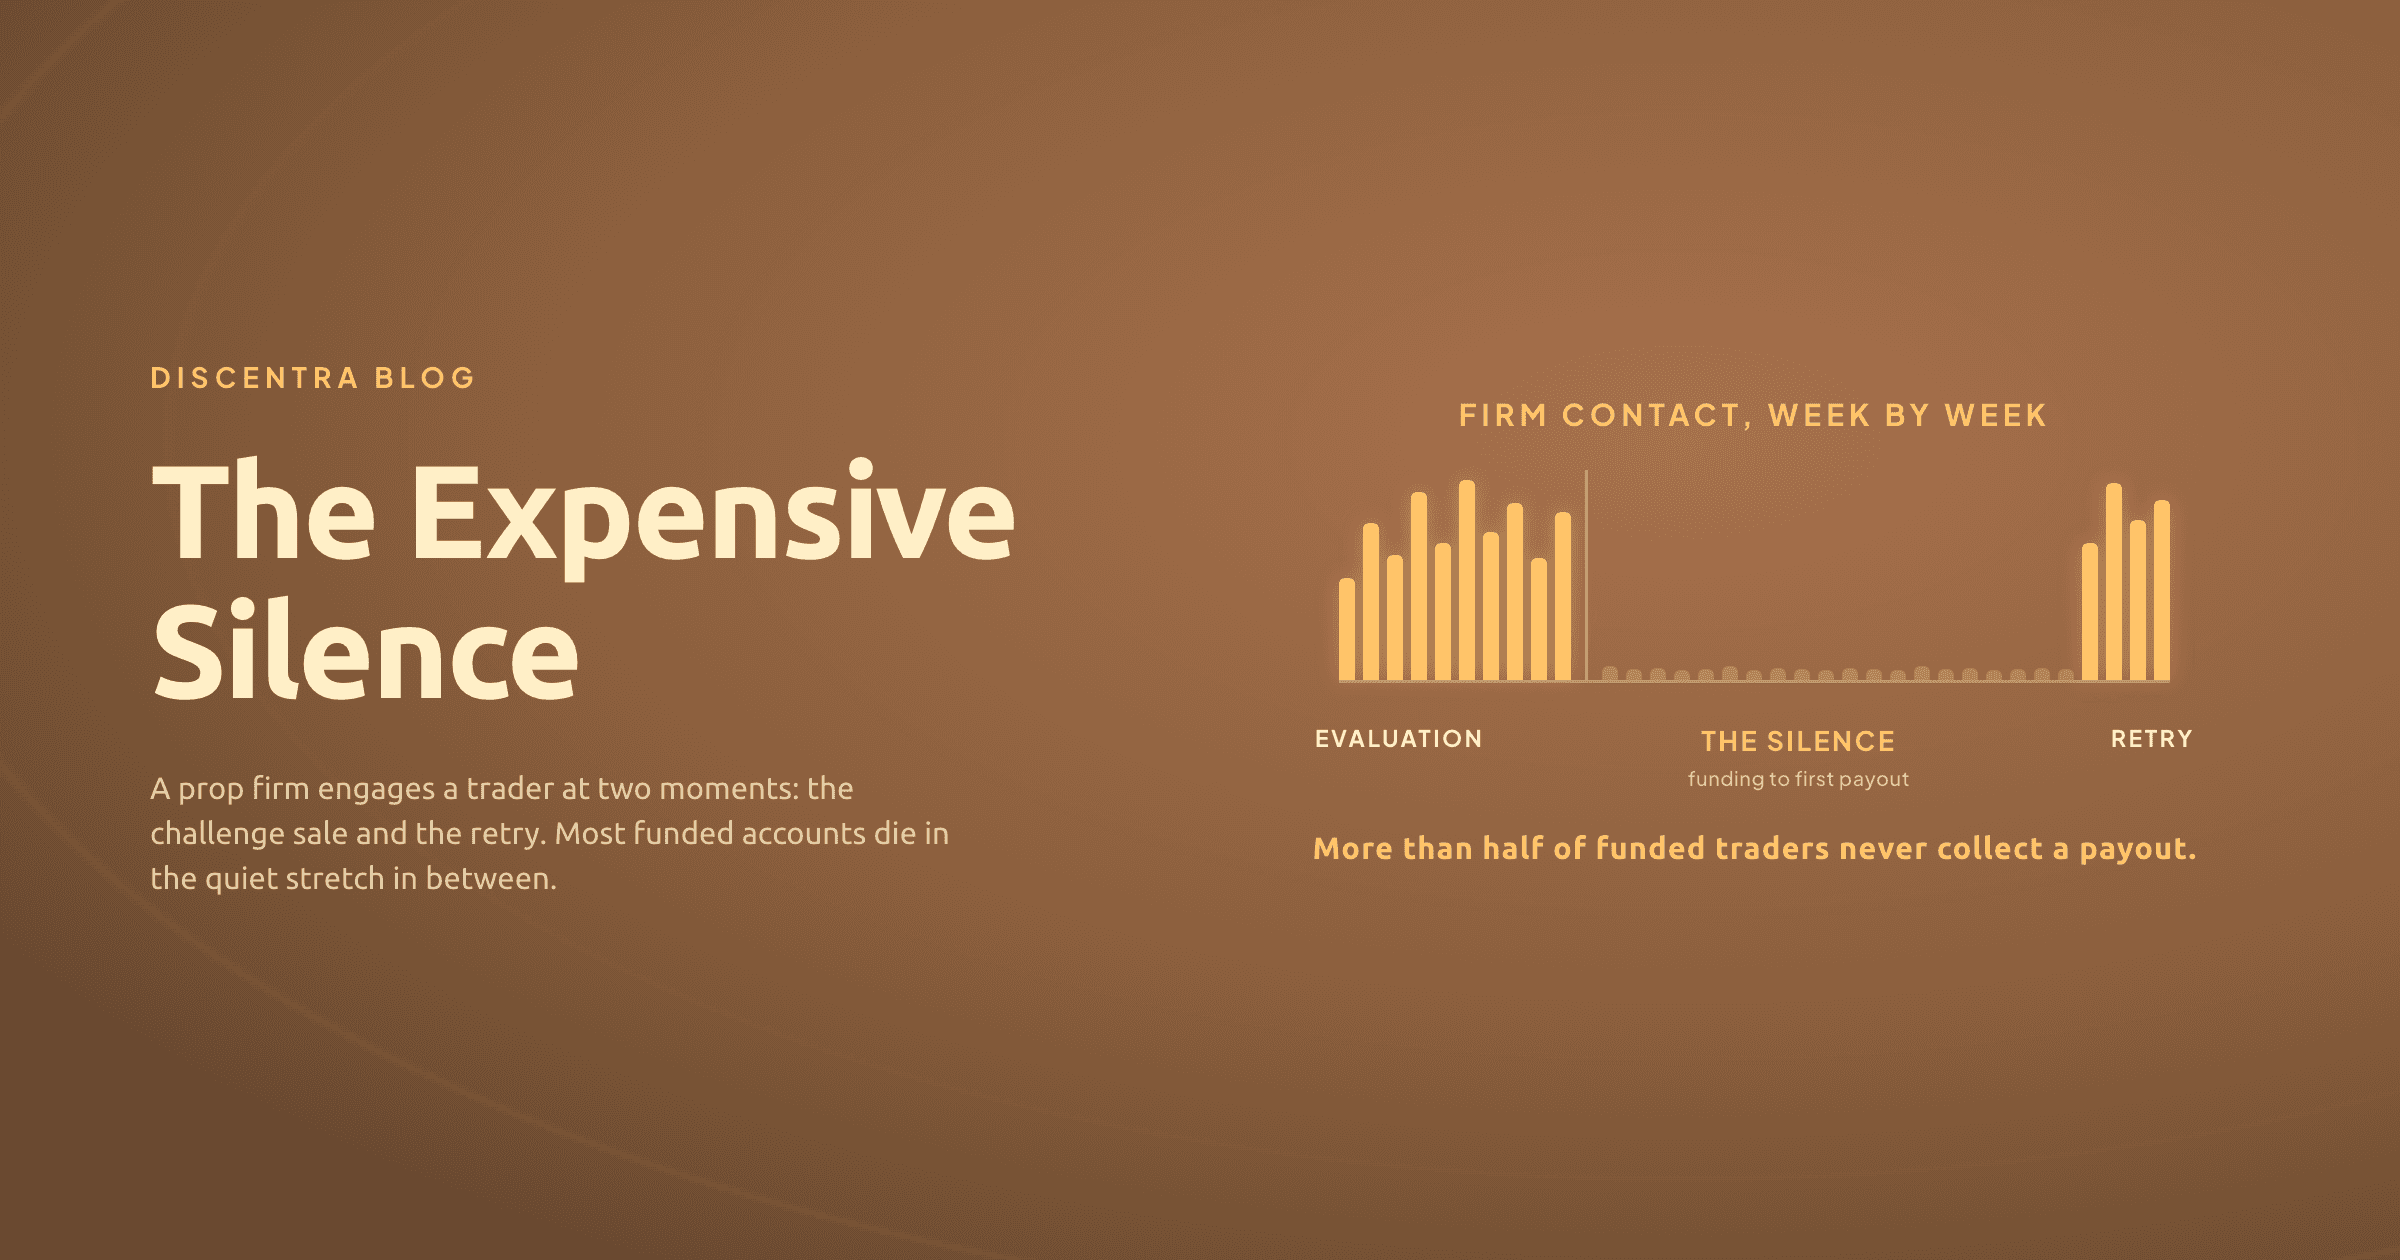
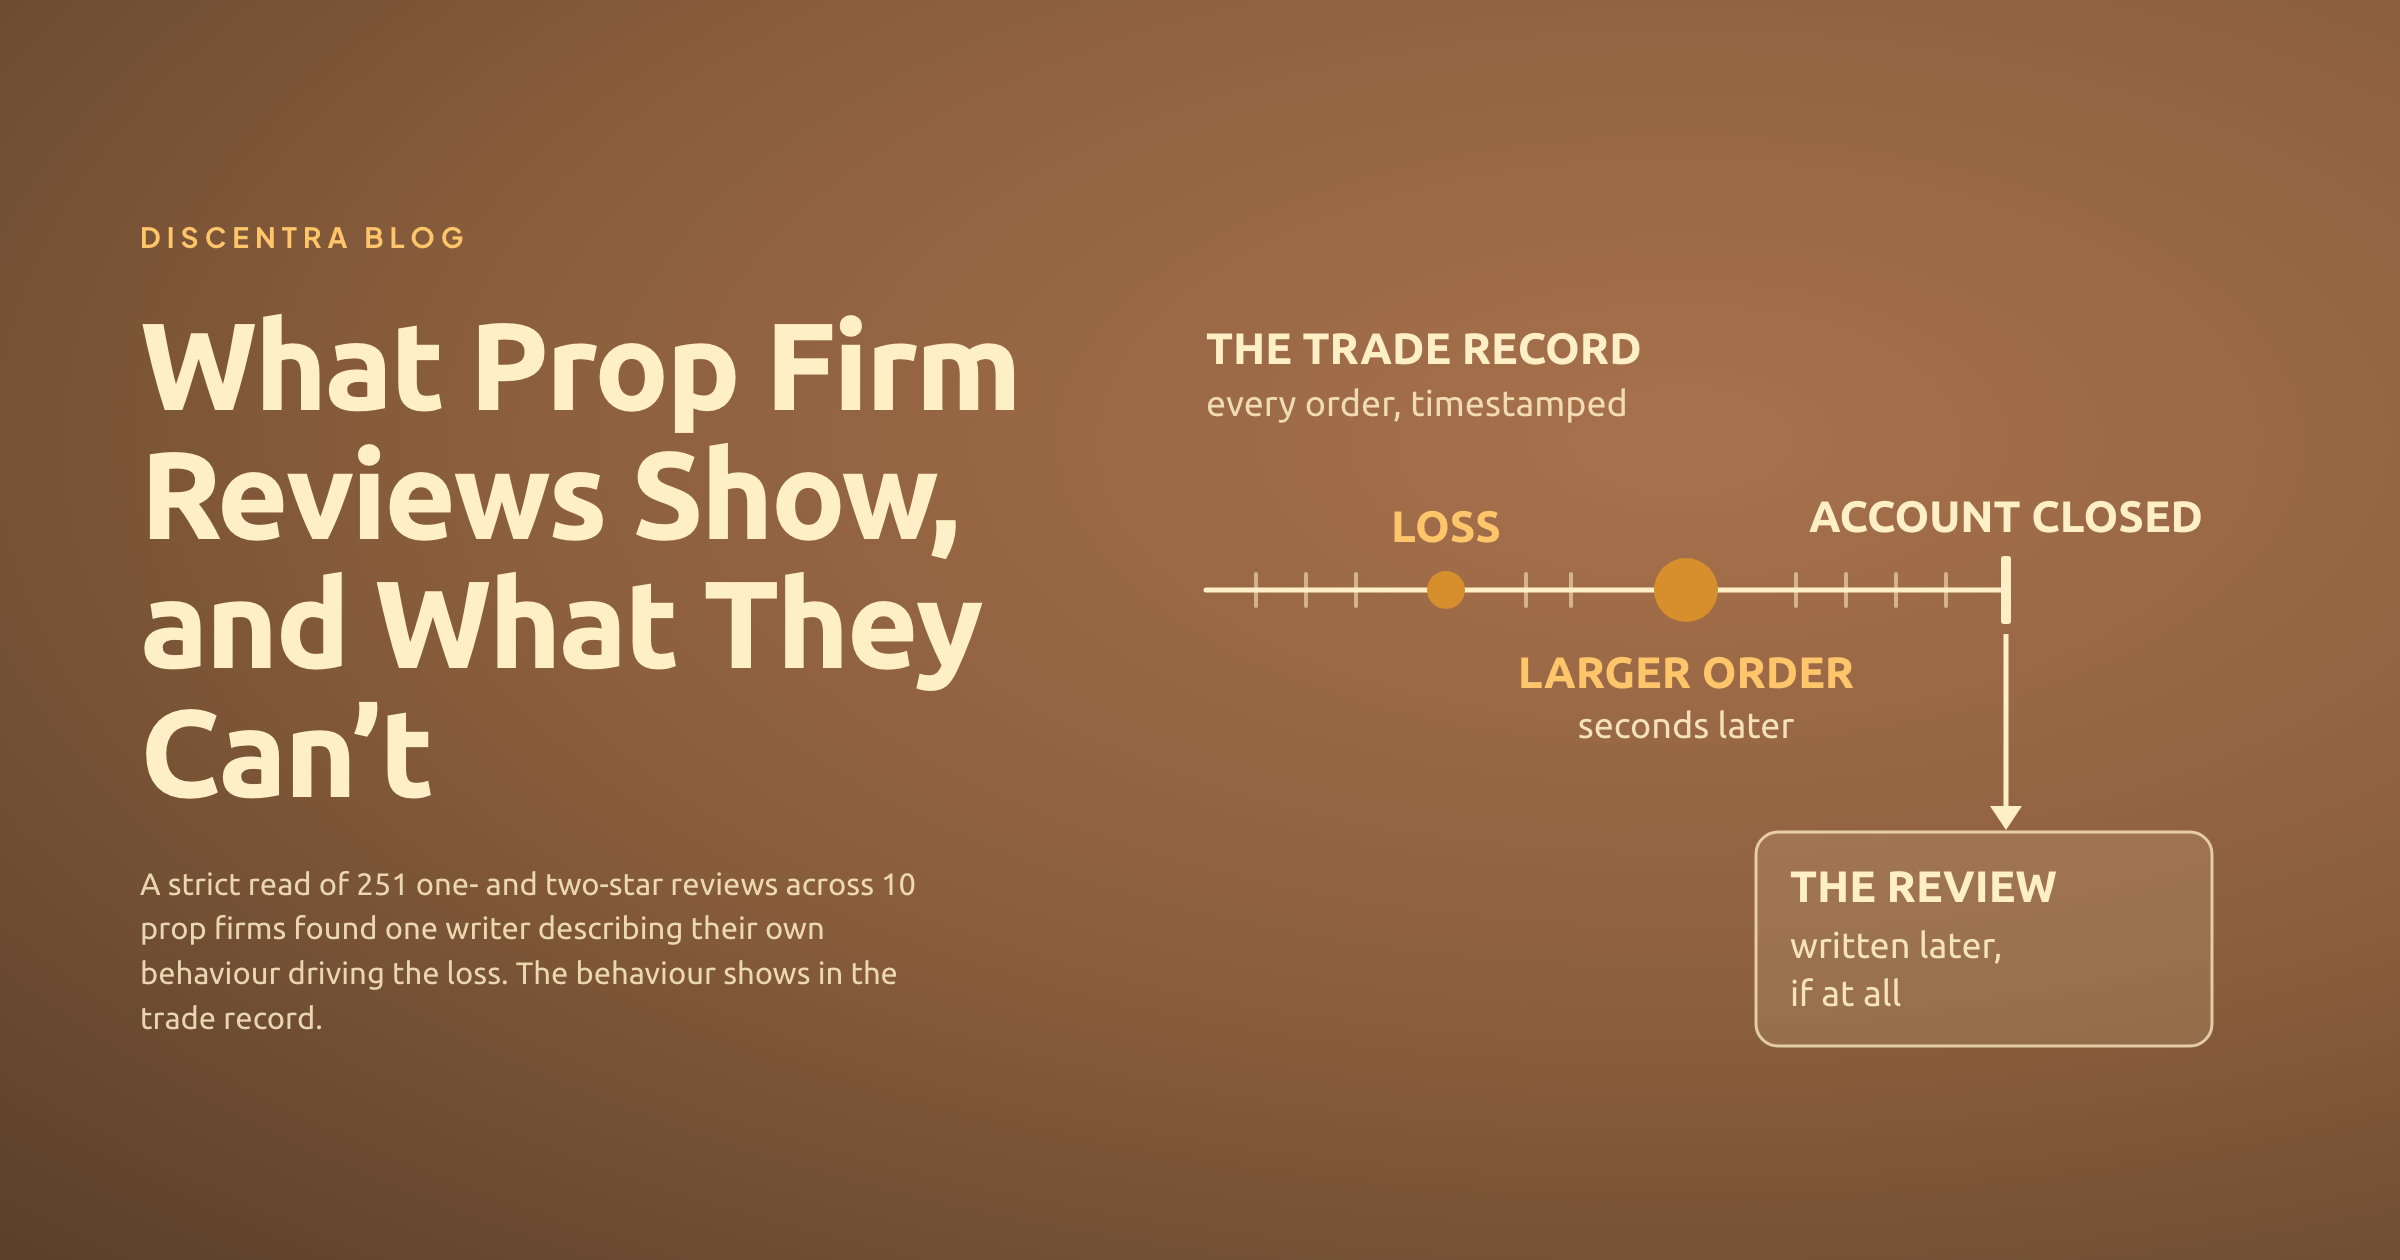
Behavioural churn has no owner, because nothing inside the firm logs it. The trade data shows the breach. The reason for the breach, a position size doubled minutes after a loss, never makes it into any system the firm runs. The evidence lives in the order flow and, after the trader is gone, in what he writes on Trustpilot.
So we read what traders write when they leave, and we put numbers on the split.
The full category breakdown
Each sampled negative review was assigned to one of seven mutually exclusive buckets by its primary complaint. The full distribution from the report:
| Complaint category | Share of negative reviews | Type |
|---|---|---|
| Platform / technical | 27% | Operational |
| Behavioural (rule violations) | 23% | Behavioural |
| Payout issues | 18% | Operational |
| KYC / account | 11% | Operational |
| Tilt / emotional trading | 7% | Behavioural |
| Arbitrary account closures | 7% | Operational |
| Support / communication | 7% | Operational |
Two buckets make up the behavioural share: rule violations driven by emotional trading (23%) plus explicit tilt and emotional trading complaints (7%). Together they account for 30% of negative reviews. The five operational buckets sum to 70%.
The 70% deserves a sentence of its own. Payout friction, platform stability, KYC speed, and support quality are real problems with real fixes, and firms that ignore them bleed trust in public. They are also the problems every operations team already sees. The 30% is different in kind: no ticket gets raised when a trader tilts.
One detail from the categorisation is worth sitting with. Revenge trading had zero explicit mentions in the sample. No reviewer used the phrase. The pattern still surfaced, as repeat purchase behaviour: the trader who fails, buys again, and fails the same way. Traders act out the mechanism without naming it, which matters for the limitations below.
The three patterns that kept appearing
The report identifies three patterns from the negative reviews. Each represents a distinct behavioural failure mode where early, real-time intervention could change the outcome.
1. Drawdown breach under pressure (23% of negative reviews)
This is the most common behavioural pattern in the sample. Traders hit their daily drawdown limit during volatile markets. For this firm the limit is 3-4% per day, and, as the firm's support reportedly told one reviewer, its "daily pause" can lag in volatile markets.
One reviewer wrote that when they contacted support, "they saying sometimes daily pause will delay to trigger in volatile market movement and that caused to breach daily loss."
The mechanism was designed to protect traders. In this reviewer's account it arrived after the damage, not before: the complaint is not that the limit exists, but that the protection came late. The signals that precede a breach (accelerating losses, growing position size, faster re-entries) exist before the limit is hit, which is what makes this pattern addressable rather than inevitable.
2. Repeat purchase after failure (7% of negative reviews)
Traders who fail buy new accounts and repeat the same behavioural patterns. One reviewer wrote: "I bought 3 $100k accounts. All entries not good."
Each failed account generates revenue from the challenge fee, which is why this pattern hides in plain sight on a revenue dashboard. The firm collected three challenge fees and produced no funded trader. The trader never reached the payout stage, never became the success story the marketing team wants, and left a public 1-star review on the way out. The short-term revenue masks a long-term retention problem.
3. Rule change frustration leading to churn
This pattern has no separate percentage: it threads through the behavioural total rather than forming its own bucket. When rules tighten, traders who are already near their emotional limit quit entirely rather than adapting. One reviewer wrote that the firm "made it impossible for me to continue trading with them because of their hard rules they applied all of a sudden. Not sustainable."
This is a psychological threshold problem. A trader in a calm state can process rule changes and adapt. A trader already tilting cannot. The rule change is the last straw, not the cause. Reviews in this bucket can read operational on the surface, which is why the borderline rule in the methodology below matters.
How we categorised the reviews
The source is public Trustpilot data for a major prop firm: 3,000+ total reviews, a 4+ average rating, and roughly 10% of reviews at 1 star. From the negative end, 44 reviews (1-2 stars) were sampled and categorised by hand into the seven buckets above.
Classification followed the primary complaint in each review. A review counted as behavioural where the language pointed to emotional decision-making, rule breaches under stress, or repeat failure cycles: tilt, account-blowing decisions made under pressure, psychological breakdowns during drawdown, a new challenge bought straight after a failure. A review counted as operational where the primary cause sat with the firm's infrastructure: platform bugs, payout disputes, KYC and account problems, arbitrary closures, support failures, rule-clarity complaints.
Borderline cases followed one rule. Where a review described both behavioural and operational issues, it was classified by the primary complaint as written.
The financial estimates use disclosed working assumptions (10-15% monthly churn for prop firms, $200 to $500 acquisition cost per trader), not proprietary benchmarks. Every assumption sits in the open in the full report, next to the number it produces.
Limitations
This analysis has four limits worth naming.
- It covers one firm. The categorisation framework is portable, but the percentages belong to this firm's review base, not to the industry.
- Public reviews skew negative. Traders who hit a payout problem write reviews. Traders who drift away after three quiet losing weeks tend not to. Trustpilot over-represents the loudest churn and under-represents the silent kind.
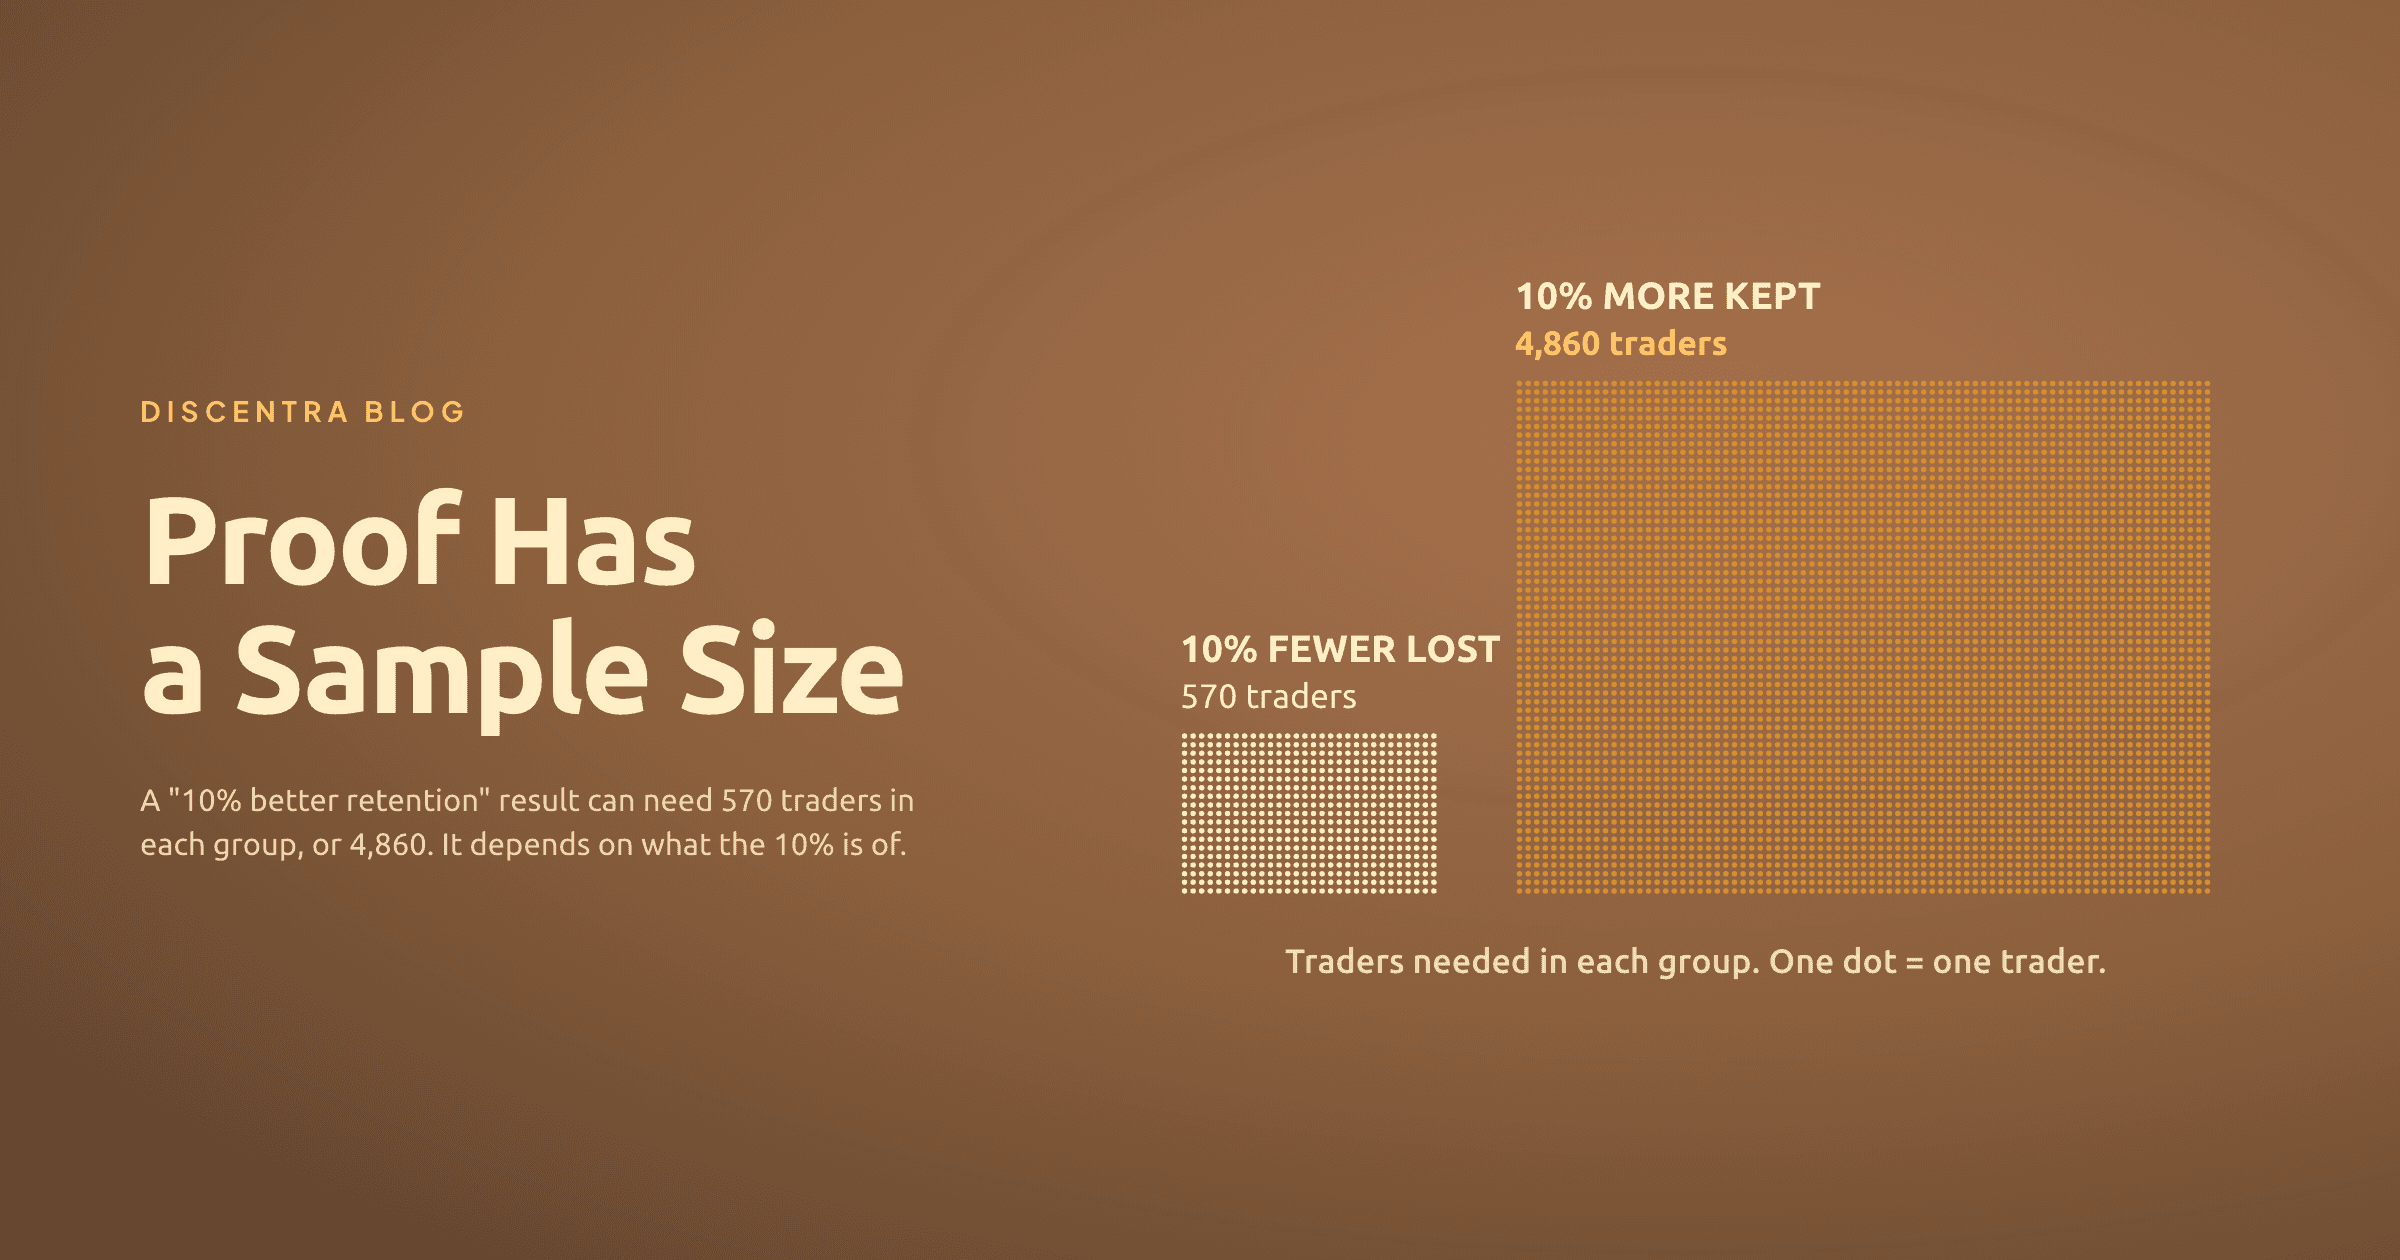
- The sample is 44 negative reviews. That is large enough to surface the dominant patterns and small enough that the percentages are directional rather than exact.
- The count is one reading of one sample. Tilted traders tend not to name the mechanism: the review blames impossible rules or bad luck across three accounts, not the trader's own tilt, and zero explicit revenge-trading mentions in a sample where repeat purchasing is visible suggest some reviews filed as operational have a behavioural episode underneath them. How each review is classified can also move the result either way. That is why we quote the 30% as one firm's sample of 44, not as a floor, a ceiling or a benchmark.
What churn costs
For a firm with 10,000 active traders and a 12% monthly churn rate (inside the 10-15% Discentra working estimate for prop firms), the cost of churn has two parts: acquisition waste (the marketing spend that brought in traders who then left) and lost lifetime value (the revenue those traders would have generated had they stayed).
The report walks the calculation step by step so you can run it on your own numbers:
| Input | How it is computed |
|---|---|
| Active traders | Your count. The worked example uses 10,000 |
| Monthly churn rate | Discentra working estimate for prop firms: 10-15% |
| Annual churned traders | Active traders × (1 − (1 − monthly churn)^12), compounding the monthly rate over the year |
| Average CAC | Discentra working assumption: $200 to $500 per trader |
| Acquisition waste | Annual churned traders × average CAC |
| Lost lifetime value | Annual churned traders × average lost revenue per trader |
Acquisition waste is the visible half: a churned trader takes $200 to $500 of marketing spend out the door. Lost lifetime value is the quieter half: the renewals and the funded-stage activity a retained trader would have produced.
What the table cannot price is the behavioural share of churn. Public reviews cannot measure it: traders who tilt rarely name it, and traders who drift away rarely write a review at all. It would show in a firm's own trade data, where the triggers appear first.
The exact number depends on the firm's pricing, trader count, and actual churn rate. But the direction is clear: churn is a multi-million dollar problem at scale, and it compounds, because the same trader can fail, repurchase, and fail again before leaving for good.
What the benchmarks show
| Metric | Discentra working benchmark |
|---|---|
| Trustpilot Rating | 4.0 to 4.3 |
| Monthly Churn | 10% to 15% |
| Average Payout | $2,000 to $5,000 (estimate) |
These are our working benchmarks for prop firms, labelled as estimates: orientation, not gospel. We no longer publish one for the behavioural share of reviews, because how a review is counted moves that figure too far for one firm to be compared with another. For what to measure instead, see 5 metrics that predict churn.
Why this matters for every prop firm
By our own count, over 250 prop firms offer near-identical rules, fee structures, and platforms. Pricing is a race to the bottom. Marketing differentiation is exhausted. The remaining competitive edge is retention, and retail trading has a retention crisis: the widely-cited figure is that ~75% of retail traders quit within 90 days.
Retention is a behavioural problem. Better spreads do not stop a trader from revenge trading after a loss streak. Lower fees do not prevent the amygdala hijack that makes a disciplined trader abandon their plan at 2pm on a Tuesday.
The mechanism is documented science rather than a coaching-industry slogan. Coates and Herbert at Cambridge measured cortisol rising in traders during volatile market periods. Kandasamy et al., in a peer-reviewed PNAS study, found that cortisol sustained over eight days made volunteers more risk-averse (the certainty equivalent fell 44%): stress hormones shift financial risk preferences in measurable ways. ESMA's 2018 review found 74-89% of retail CFD accounts lose money. Those findings describe the person trading, not any one firm's platform.
The firms that understand churn as a neuroscience problem rather than a product problem, and build systems that intervene inside the 4-minute window between trigger and next trade (the window is Discentra's operationalised construct, not a research finding), will retain the traders that everyone else loses. That intervention is behavioural coaching, not financial advice: no trade recommendations, no price predictions, a voice that coaches the trader back to their own plan.
Get the full report
The 30% here is one firm's sample of 44 negative reviews, counted under one rule. Reviews show which patterns recur; the size of the behavioural share would show in a firm's own trade data. The patterns themselves (drawdown breaches under pressure, repeat purchases after failure, rule-change tilt) are detectable in real time, which is what makes them addressable rather than inevitable. The full cost arithmetic is in the real cost of trader churn.
The complete analysis behind this post is a free 6-page PDF: the category table, the trader quotes, the methodology, every working assumption disclosed, no pitch.